Cebu vs global property markets: a foreign investor’s risk-adjusted view
CebuPropertyMan editorial analysis · Research checked October 11, 2026
If your investment capital could go to Cebu, the United Kingdom, the United States or Australia, Cebu needs to earn its place in the portfolio. A gross-yield chart is only the starting point. For a foreign investor, access rules, taxes, management and resale can matter more than a one-percentage-point yield difference.
Photo credits


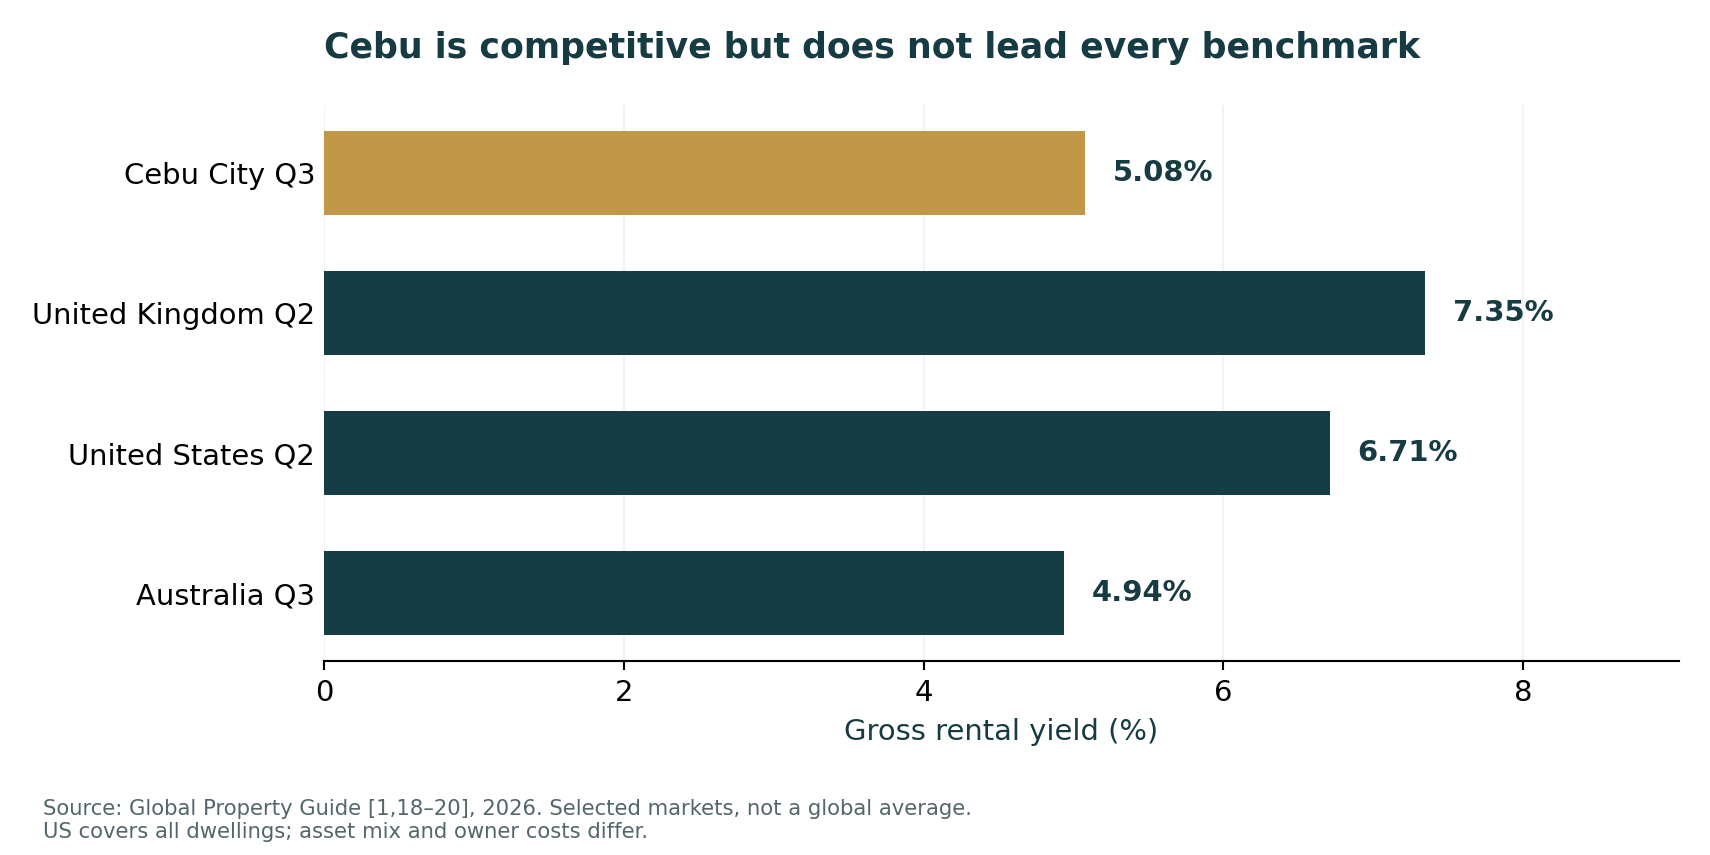
These selected global reference markets are not a worldwide ranking. A property accessible to a local citizen may be unavailable or substantially more expensive for a foreign buyer. Compare the same investor profile and eligible asset, then calculate operating income and after-tax cash flow.
On mobile, swipe the table to see all columns.
| Residential sampled benchmark | Gross yield | Period |
|---|---|---|
| United Kingdom | 7.35% | Q2 2026 |
| United States | 6.71% | Q2 2026 |
| Australia | 4.94% | Q3 2026 |
| Cebu City comparator | 5.08% | Q3 2026 |
Figures from [1,18–20]. These selected markets are reference cases rather than a weighted global average or coverage of every continent. The US source covers all dwellings, while several others focus on apartments. Avoid presenting this as a strict like-for-like league table.
Capital examples at three price positions
On mobile, swipe the table to see all columns.
| Residential proxy | Asking purchase price | Monthly rent | Gross yield |
|---|---|---|---|
| Manchester lower ticket studio | EUR139,200 | EUR1,100 | 9.48% |
| Manchester middle ticket 2BR | EUR284,200 | EUR1,680 | 7.09% |
| London higher ticket Westminster 3BR | EUR2,494,000 | EUR8,595 | 4.14% |
| US lower ticket Chicago studio | USD180,000 | USD1,960 | 13.07% |
| US middle ticket Chicago 2BR | USD425,000 | USD3,200 | 9.04% |
| US higher ticket Manhattan 3BR | USD3,995,000 | USD13,000 | 3.90% |
| Sydney lower ticket Western 1BR | USD354,000 | USD1,420 | 4.81% |
| Sydney middle ticket 2BR | USD534,100 | USD2,440 | 5.48% |
| Sydney higher ticket CBD 3BR | USD3,008,700 | USD6,230 | 2.48% |
The UK source displays euros; Australian values are displayed in US dollars, not AUD. These are source currency representations, not actual transaction settlement quotations. Small and large tickets are proxies, not formal quality tiers. Outlier double-digit yields require especially careful validation of comparable asset mix, rent assumptions and recurring owner costs. [18–20]
Commercial perspective
JLL reports global office vacancy of 16.5% in Q2 2026 and new post-pandemic highs in first-half office leasing. It also identifies demand in logistics and prime retail. [21] These aggregates do not imply healthy income in every older office or secondary shopping location. Strong leasing alongside limited supply can support prime rents; assets requiring major capital expenditure may still struggle.
For an overseas buyer considering Cebu, lower entry capital can be useful, but it is not proof of better risk-adjusted performance. Price the costs of managing from abroad and converting income home. Local familiarity through a broker or manager is useful only when backed by independently checked title, rent and accounts.
Foreign status changes your alternatives
On mobile, swipe the table to see all columns.
| Destination | Foreign-investor issue | Why headline yield is insufficient |
|---|---|---|
| Cebu | Eligible condominium ownership versus generally restricted land ownership | Not every Cebu listing is an available asset |
| England / Northern Ireland | 2% non-resident SDLT surcharge applies to qualifying residential transactions, on top of other applicable rates | Higher acquisition capital reduces the effective yield |
| United States | Foreign-seller disposal can trigger FIRPTA withholding, generally 15% of amount realized subject to exceptions | Exit proceeds and timing differ from the advertised sale price |
| Australia | Foreign persons generally barred from established dwellings, 1 April 2025–31 March 2027, with limited exceptions; approval requirements apply | An established-unit benchmark may not be an eligible investment |
The UK surcharge stated here concerns England and Northern Ireland; Scotland and Wales have different transaction-tax systems. FIRPTA withholding is not the final US tax liability, and exceptions or withholding certificates may change the amount. Australian eligibility depends on asset and buyer status; do not interpret the policy as a ban on every form of foreign investment. Sources 31–33.
Anchor the comparison to realistic Cebu capital
On mobile, swipe the table to see all columns.
| Illustrative Cebu residential budget | PHP all-in capital | Approximate USD capital | Rent needed for 6% scheduled gross |
|---|---|---|---|
| Lower-budget scenario | ₱3,000,000 | $47,797 | ₱15,000 / month |
| Mid-budget scenario | ₱6,000,000 | $95,593 | ₱30,000 / month |
| Higher-budget scenario | ₱12,000,000 | $191,186 | ₱60,000 / month |
USD equivalents use BSP’s published ₱62.766 per US$1 reference for 9 October 2026, rounded to whole dollars. This is not a bank conversion quote; spreads and transfer charges are additional. These are hypothetical all-in budgets, not Cebu valuations or verified market tiers. All-in capital includes purchase, closing, furnishing, initial repairs and reserves. Source 26.
Compare the same four measures in every destination
On mobile, swipe the table to see all columns.
| Measure | Use this definition |
|---|---|
| Gross rental yield | Annual scheduled rent / purchase price; state whether all-in capital replaces price |
| Operating yield | Income after vacancy and recurring operating costs / all-in capital, before debt and income tax |
| After-tax cash flow | Operating income less applicable tax and debt service; include home-country obligations |
| Total return in funding currency | Income plus capital-value change, translated consistently and less acquisition/exit costs |
Do not subtract a universal fixed percentage from every city’s gross yield and call the result net. Insurance, property tax, dues, vacancy and management differ by asset and jurisdiction. Compare an unlevered base case, a downside vacancy/cost case and an FX downside case. Appreciation belongs in a separate assumption, not in the rent needed to pay the bills.
Residential and commercial tiers: different failure modes
For lower-budget residential stock, test maintenance and turnover; for mid-market apartments, test sustainable tenant affordability; for premium units, test longer vacancy and special assessments. Commercial investment needs separate lease analysis: small premises depend on a few tenants, mid-market buildings need reletting and fit-out reserves, and prime assets require reliable income to justify compressed yields. A global office vacancy statistic is not a Cebu commercial property valuation.
Can you get your money out?
Before purchase, identify the eligible resale buyer, transfer procedure, estimated selling costs and conservative marketing period. Ask the receiving bank what evidence is needed for lawful remittance of rent and eventual sale proceeds. Maintain acquisition and tax records. Ownership, immigration status and residence rights are separate issues; buying property should not be represented as automatic visa eligibility.
The foreign-investor verdict on Cebu
Cebu is a candidate for selective rental investment, not a universal bargain. It may suit an investor who wants Philippine exposure, can acquire an eligible asset and has verifiable local management. It may be unsuitable for someone seeking direct foreign land ownership, easy non-resident leverage or a rapid exit. Choose it only when a specific property clears your ownership, cash-flow, currency and liquidity hurdles.
Research sources
- Global Property Guide — Philippines rental yields October 2026 Q3 2026 ↗
- Global Property Guide — United Kingdom rental yields Q2 2026 ↗
- Global Property Guide — United States rental yields Q2 2026 ↗
- Global Property Guide — Australia rental yields Q3 2026 ↗
- JLL — Global Real Estate Perspective August 2026 ↗
- Philippine Constitution — Article XII: land ownership eligibility ↗
- Philippine Condominium Act — Republic Act 4726, Section 5 ↗
- Bangko Sentral ng Pilipinas — PHP/USD reference, 9 October 2026 ↗
- Australian Government — Foreign residential eligibility, 2025–2027 policy ↗
- HMRC — England and Northern Ireland non-resident SDLT surcharge ↗
- IRS — FIRPTA withholding on foreign-owner disposal ↗