Financing can improve a deal or make it fragile
CebuPropertyMan · Published 11 October 2026
A seller’s willingness to accept an offer and a lender’s willingness to finance you are separate decisions. A bank marketing the asset does not automatically approve your housing loan. Do not commit to a cash deadline on the assumption that loan proceeds will arrive in time.
Confirm the payment route first
Ask whether the particular asset permits financing, which arrangements are acceptable, and when the balance becomes due. Some BPI Yellow Tag assets with title-consolidation or possession concerns are restricted to cash under its published terms. That is a specific bank rule, not a universal rule for every foreclosure. [5]
Get the proposed lender’s appraisal basis, approved loan amount, required equity and disbursement conditions. A percentage advertised for a loan product does not guarantee that percentage of your purchase price. A lower valuation or an ineligible title can leave you needing more cash than expected.
Compare written quotations by interest-rate fixing period, repricing method, term, required insurance, appraisal and documentation fees, and prepayment conditions. Ask for repayment scenarios at the initial rate and a higher rate after repricing. “Fixed for three years” should not be presented as a rate fixed for the whole loan term.
Budget for a property that earns nothing at first
An asset can consume cash while documentation, possession, repairs or tenant placement are pending. Add that period to your schedule before counting rental income. Keep personal emergency funds separate from property reserves and make sure you can meet loan payments without the new tenant.
Avoid short-term borrowing that must be repaid before a plausible sale or refinance. A bridging arrangement is risky when its repayment depends on an exit you cannot control. Ask the lender whether interest accrues during any advertised payment holiday; deferred payments do not necessarily mean free financing.
Stress-test the debt against operating income
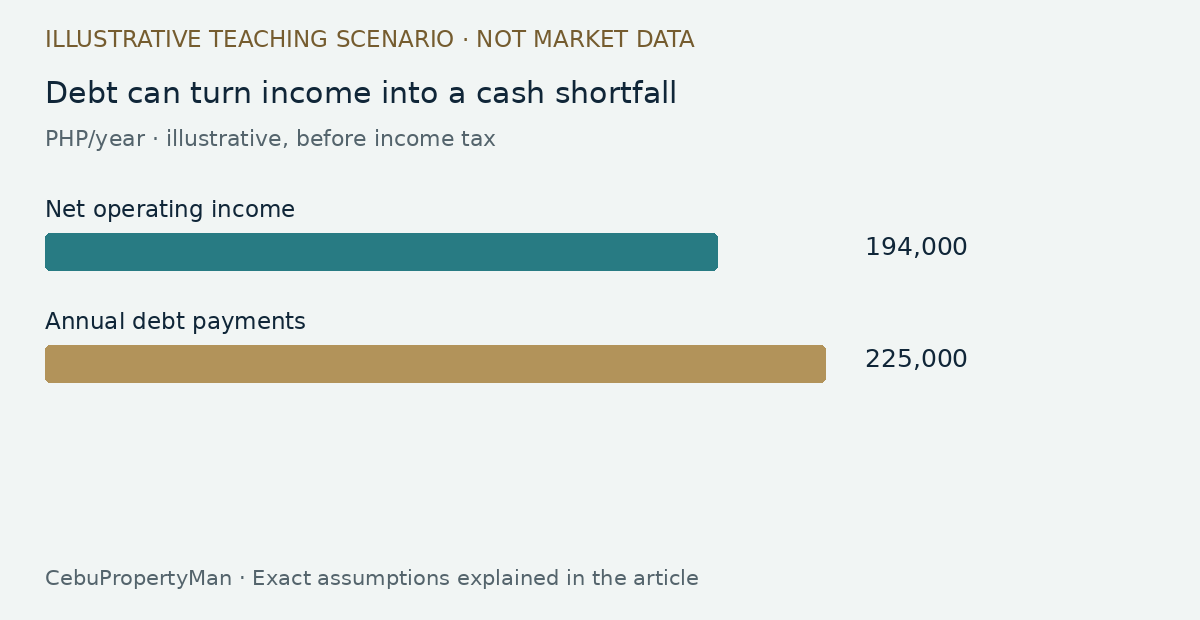
Suppose an illustrative property produces PHP 194,000 a year in net operating income before debt and income tax. Annual principal-and-interest payments of PHP 225,000 leave a PHP 31,000 cash shortfall before income tax. The debt-service coverage ratio is 194,000 divided by 225,000, or approximately 0.86. A ratio below 1 means the property’s operating income does not cover those payments. It can still be an intentional investment, but it requires a credible reason and outside funding.
Financing is useful when it matches your income, timeline and reserves. Reject the idea that using more debt automatically improves a property investment.
Sources and verification
Source statements checked 11 October 2026. The specific bank sale contract and current law govern the transaction.